
Editor’s note:
The first hedge in Jewish history was dramatic. Jacob, our forefather, can’t tell if war or renewal awaits as he relocates his household to the Holy Land after 20 years away. So he splits his camp, all of his assets - including his human capital. Today, as we look at the shared economic future of the camps within the Jewish State, there is no hedge; we can be sure that we will face both war and renewal. This week’s economic events in Israel proved, again, that we can count on ourselves and on our companies. That even in wartime, state budgets will pass. And that we will not be stopped from writing this poignant chapter of Jewish history, along with our allies around the world.
— Eran Bar Tal, Editor-in-Chief, TV10
The quick read:
Two camps, indeed. Anyone watching the Israeli economy this week needed a split screen on war and economic renewal. First, we got handed two different official projections for GDP growth in 2026 - OECD projects +4.9% and BoI +2.5%. Positive new wage data revealed two economic realities (tech, and everyone else).
Regardless, Israelis do make enough to have spent 28% more on Black Friday than last year. All this, while we were bombing the bajezus out of the terror infrastructure build-up on our northern border.
The government is spending, too. Going into this weekend, the 2026 state budget received cabinet approval, including ₪112B for defense (a ₪47B increase).
Read our Editor-in-Chief's explainer on the State Budget at the end of this newsletter.
A notable defense deal this week, as Germany paid over $4B to acquire the Arrow-3, the Israeli interceptor for ballistic missiles. In smaller defense-tech deals, Israeli TSG got a ₪4.4M Czech contract, Gilat Satellite Networks (NASDAQ:GILT, TASE:GILT) announced an undisclosed, ~$10M customer, and the new space-tech startup Moonshot came out of stealth with a clever name and a $12M funding round.
More on notable funding, exits, markets and macro below.
Onwards.
Private company M&A and exits
Year-end data is starting to come out for private company fundraising and exits, particularly in tech. New data by Poalim Tech and Dealigence showed that 35% of tech acquirers in Israel are now Israeli companies, up from 23%. This signals a maturing tech industry where local titans have the balance sheets to act as consolidators, not just targets.
Israeli digital forensics company Cellebrite (NASDAQ:CLBT) closed its $170 million acquisition of U.S.-based Corellium this week, illustrating the shift toward Israeli companies becoming buyers rather than sellers. Meanwhile, in its Q3 earnings, Accel Group (TASE:ACCL) attributed a 27% revenue rise (to ₪109 million) to recent Israeli M&A activity.
Private equity activity also made headlines, most notably, the $950M acquisition of Israeli online marketplace Yad2 - Apax Partners beat out Blackstone and CVC to take over the ubiquitous site. And in the infrastructure and real estate sector, the PE One Invest bought 35% of infrastructure firm Ariel Gabay for ~₪150 million. The public Aluma Infrastructure fund (TASE:ALUMA) agreed to sell its majority stake in Exelera for a 2.3x return (valuing the company at ₪500 million).
Next up, a note on the public markets.
Markets
✉️ Notes by Moshe Maimon, Head of TV10 Capital Markets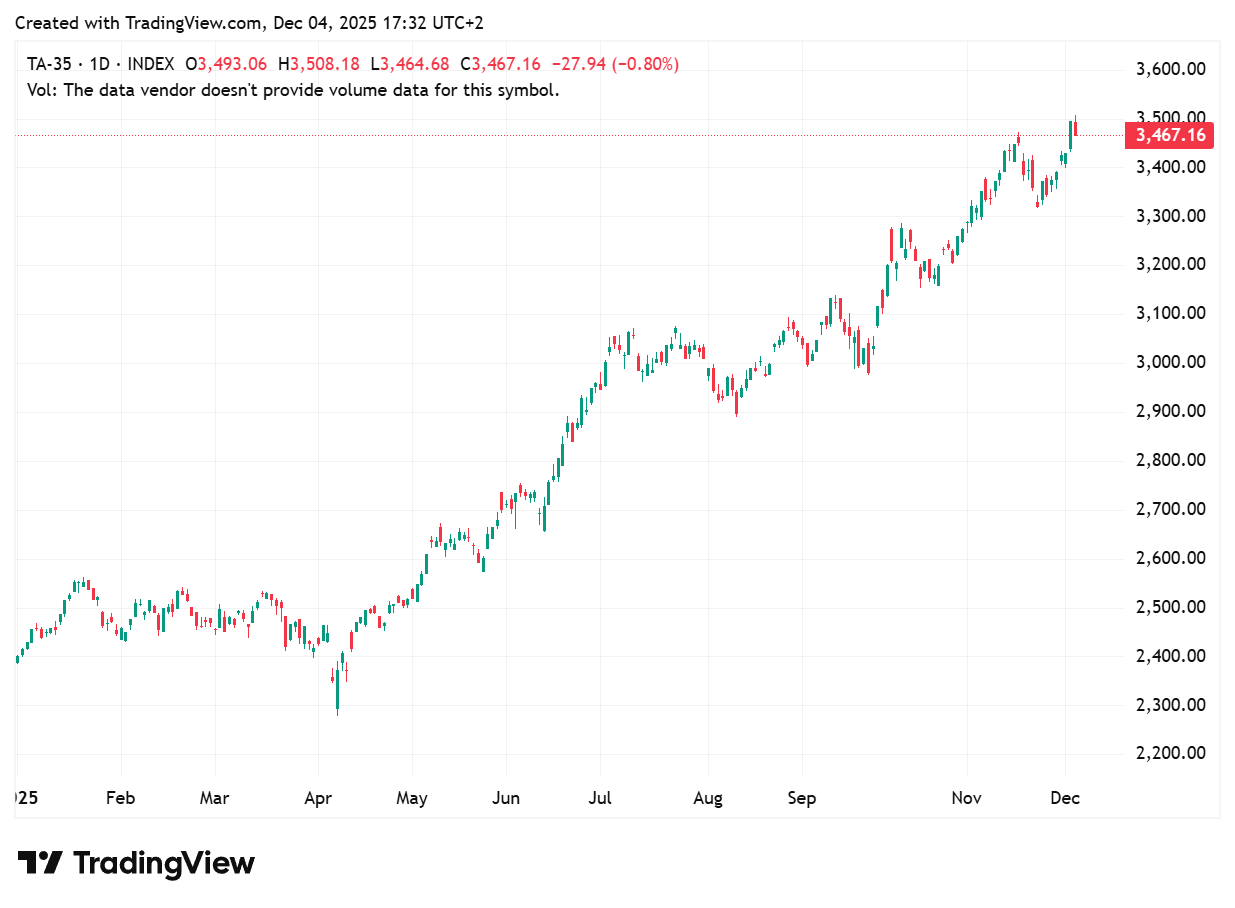
After two volatile trading weeks, the Tel Aviv Stock Exchange concluded the week on a positive note overall, with a rise in flagship indices TA-35 (TASE:TA35), and TA-125 (TASE:TA125).
The gains were driven primarily by the Finance and Insurance sector, after last week’s declines in insurance stocks following regulatory pressure on that industry. Last week, I pointed out that this dip was likely an overreaction, a ‘sell the rumor’ situation, profit-taking, and nothing more. The Insurance index (TASE:TAINS) ended up posting a 3% correction to the upside.
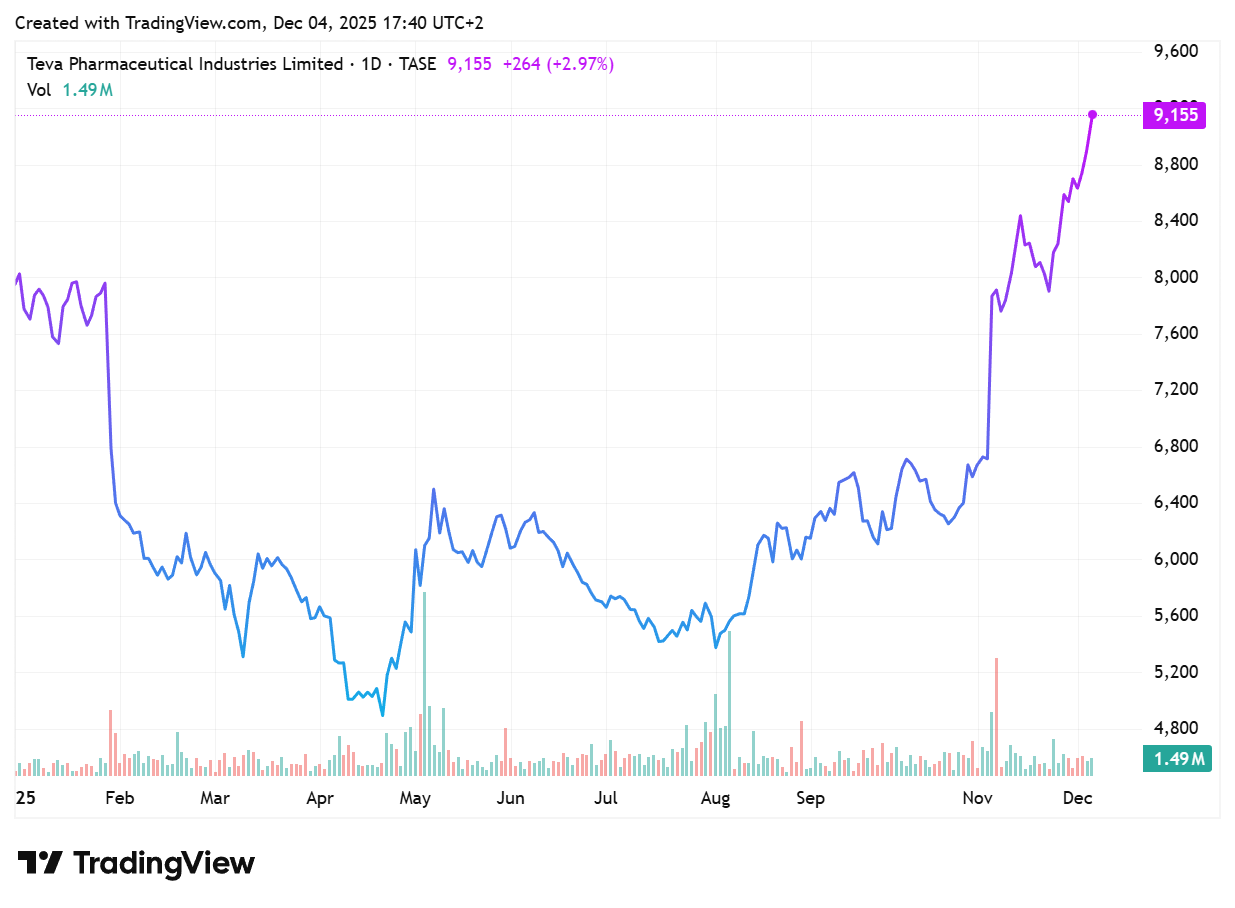
Teva Pharmaceutical Industries (TASE:TEVA), crossed ₪100 billion market cap, becoming Israel’s second largest company, behind Bank Leumi (TASE:LUMI). The milestone validates CEO Richard Francis’s strategy, including the commercialization of branded drugs and the improvement of profitability in generic drugs.
Meitav (TASE:MTAV), the asset manager, caught momentum, successfully raising ~₪500 million. Valued at ₪9.3 billion, a 6.5x surge in three years, the firm is riding a boom in assets under management (AUM) and retail investor interest. This places it on the verge of inclusion in Tel Aviv’s TA-35 index, a milestone that can trigger a rally driven by new demand from index-tracking funds.
In contrast, ICL Group (TASE: ICL) confronted consecutive hits. The stock extended its slump after the Supreme Court ordered a ~₪90 million payment for historical water usage. This comes alongside the cancellation of the miner’s “right of first refusal” for the 2030 Dead Sea mining rights.
Execs on the move
Yafit Gheriani named CEO of CAL (Israel Credit Cards), crossing over from rival Isracard (TASE:ISCD). Subject to Bank of Israel approval.
Raphael Maman appointed CEO of energy giant, Bazan Group (TASE:ORL), bringing 30+ years of global experience at Shell and A&M to Israel’s critical energy infrastructure provider.
Debt & Equity Raises on the TASE this week
• Israel Land Development (TASE:ILDC): Raised ₪555 million with demand reaching ₪1 billion;
• Kardan Real Estate (TASE:KARE): Bond expansion raised ₪208 million with a 1.48% spread over government bonds, viewed as a confidence premium regarding their execution pipeline;
• Bank of Jerusalem (TASE:JBNK): CPI-linked debt raise oversubscribed by more than 2x (₪840 million orders for ₪388 million target);
• Issta (TASE:ISTA): Debut bond issuance saw demand of ~₪630 million for a ₪215 million raise, intended to fuel logistics and hotel expansion;
• Econergy (TASE:ECNR): Raised ₪250 million in a private placement at a 4% discount to the closing price, with major institutions increasing positions;
• Michlol Finance (TASE:MCLL): ₪55M public equity offering priced at a premium over the closing price, targeting net profits of ₪90M–120M by 2027;
• Sugat IPO listed 29% of shares at a ₪1.2 billion valuation, raising ₪360 million.
There is much to say about the 2026 budget approved by the government last Friday (December 5th, 2025), but the most important thing is that it was, in fact, approved.
Our memory is short. We’ve forgotten that a government submitting its fourth budget in a four-year term is not something to take for granted. We’ve had seven elections in the last 15 years; stability is not a familiar concept here. Since 1948, only five governments have completed a full four-year term!
This isn’t only about the cost of elections, but the ability to govern, the ability to lead meaningful reforms in health, education, energy, and transportation. So since the achievement is that there is an approved budget, we should hope it passes the Knesset more or less in the form approved by the government.
The biggest challenge of this budget was security. Out of ₪622 billion, ₪112 billion was allocated to defense: 18%, or nearly 6% of GDP. That’s a lot, but it makes sense for our situation.
Finance Minister Bezalel Smotrich tried to fight waste in an inefficient system, and the examples he raised were disturbing, like how the defense establishment used reserve duty days with appalling extravagance. We all know the stories of reservists credited with 250 days or more when they actually served only a fraction of that. This is inexcusable waste, even in wartime. The army operates with similar profligacy with regular soldiers and, critically, does not allow for transparency or oversight.
Smotrich is right to demand accountability, and we must continue demanding maximum transparency so the massive, and increasing, sums flowing to the military are directed where they actually matter.
Any state budget in Israel must be examined on three variables: the defense allocation, the deficit target, and structural reforms.
The Finance Minister set an ambitious deficit target, but in the end, 3.6% is reasonable and responsible for this period. If there are no dramatic security developments, the next government should be able to reduce it further.
The budget approved dairy industry reforms, which we should all hope become law. The Bank of Israel Governor welcomed the reform because it represents a structural change already implemented across the Western world, but difficult for Israel to execute: supporting farmers without banning competing imports.
Taxing unused land is also structurally important. The proposal to tax land held without construction starting at 1.5% is correct and could increase construction while lowering housing prices. It’s very possible that many elected officials, who tend to hold land themselves, will torpedo this, but it’s important that the proposal made it into the budget.
Finally, the railway reform was partially approved. The budget lacks additional structural reforms, but crucially, it does not increase the tax burden. It even doubles the personal import exemption, from $75 to $150.
For now, Israel has fiscal stability, defense funding, and a government that can govern. In 2025, those are solid fundamentals.
Next week: The wage disparity
We’ll look into the real meaning of the recent Bureau of Statistics wage report, where the average Israeli salary climbed 2.7% to ₪13,321 in October, barely outpacing 2.5% inflation. While tech salaries jumped 6.3% to ₪33,366, skewing averages, most workers saw real wages stagnate or decline. More on the implications of this for Israelis in our analysis next week.
That’s our letter, folks. If you enjoyed this Weekly, please forward it to a friend.
The English TV10 newsletter is edited by Sophia Tupolev. Share your thoughts!
TV10 Global | Israel for Investors
Now in English: Bringing you the top stories from the Israeli business community, by Israel’s only business and finance network.
Please share your thoughts with us via: [email protected] or the Newsroom WhatsApp: +972-55-994-5851.
📧 Subscribe to this newsletter! And follow the daily conversation on 𝕏 @tv10global.
Pings with new editions are also available via our WhatsApp Channel.
Disclaimer: This brief is for informational purposes only and does not constitute investment advice. All data is current as of publication date.