
Editor’s note:
Since World War II, the U.S. Treasury maintained a strong dollar while the Fed fought inflation. Now, the White House is openly pushing dollar depreciation to boost manufacturing. This created a standoff - Trump seemed to be weaponizing currency volatility to force Fed Chair Powell to cut rates from 3.75%. Powell refused, stating exchange rates are “the province of the Treasury.”
While a strong shekel sounds like a positive headline, beware of fallout for Israel. Our tech sector earns in dollars but pays costs in shekels. The dollar’s collapse to ₪3.08 is crushing export margins while The Bank of Israel is in a sub-optimal position– intervening risks political retaliation from a volatile Washington, while inaction allows the currency shock to hollow out our primary growth engines.
— Sophia Tupolev, TV10 Global Editor
TASE weekly snapshot
The Tel Aviv Stock Exchange closed the week mixed.
TA-35 Index (TASE:TA35): 🟢 +0.43%
TA-90 (TASE:TA90): 🔴 -3.02%
TA-125 (TASE:TA125): 🔴 -0.34%
Macro & FX
The dollar hit a four-year low of ₪3.087 while the euro rose to ₪3.707. Trump insists the dollar is “doing great” but his administration openly wants a weaker currency to compete with China and Japan. Bloomberg’s Dollar Index fell 1.2% in a single session.
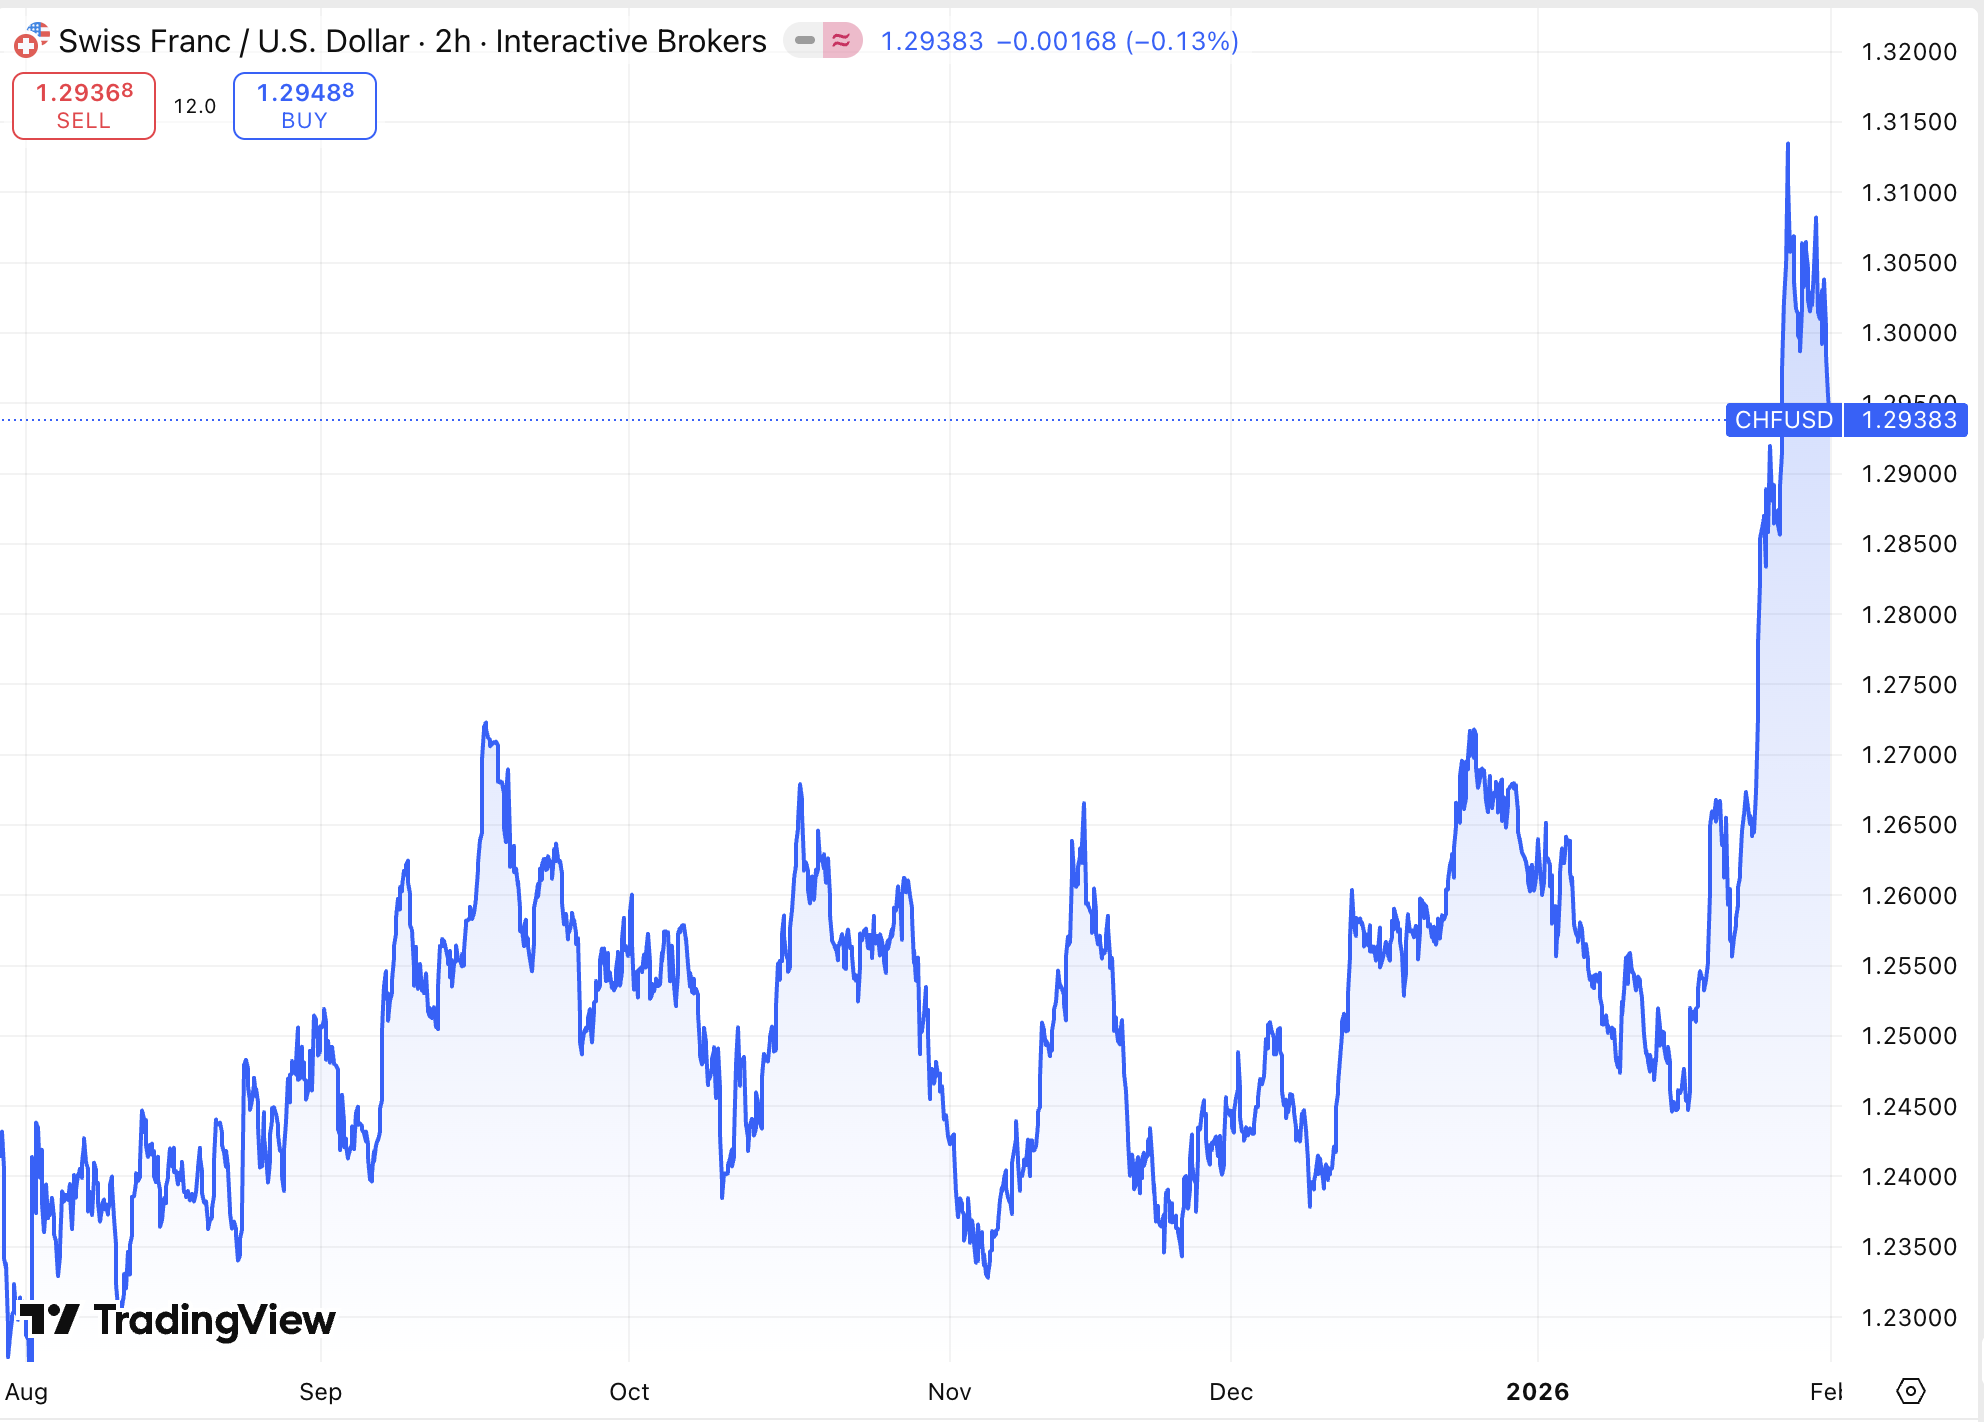
The Swiss Franc surged to a decade high, up 3.5% year-to-date against the dollar, as investors fled to safety. Gold breached $5,200/oz. Swiss National Bank Chairman Martin Schlegel warned at Davos that rapid appreciation creates disinflationary pressure - while Swiss inflation is already 0.1%.
As the West frets over exchange rate spreads, we watch Tehran fight for economic survival, and not only. Iran’s Rial collapsed past 1,500,000 to the dollar on the black market, driven by sanctions, US military threats, and a total evaporation of public trust - to say the least. Concurrently, German intelligence reports a spike in Iranian cyber-terror activity, a tell-tale sign of a regime under immense internal strain - a wounded animal.
Our take: We are watching the Triffin Dilemma play out in real-time - international demands vs. domestic monetary policy. The global economy craves dollars for liquidity but is losing faith in the currency's long-term value as deficits mount. For Israeli CFOs, the hedging playbooks of 2025 are dead. In this environment, routine cash flow management has effectively morphed into high-stakes FX speculation. And for the Ayatollahs, the danger is existential; historically, hyperinflation is the most efficient engine for regime change.
Analysis | Israeli tech faces margin squeeze from strong shekel
The dollar’s collapse to ₪3.08 transfers wealth from Israel’s exporters (tech and defense) to its consumption base - importers and households.
For companies like Elbit Systems (NASDAQ:ESLT) or Aryt (TASE:ARYT), the math is brutal. They bill clients in depreciating dollars but pay salaries and taxes in strengthening shekels. The exchange rate has slashed top-line revenue ~10% year-over-year while local costs remain sticky. We could see “efficiency” layoffs in Q2 driven by FX-induced margin compression, not demand weakness.
For households, the strong shekel deflates imports - meaning, cheaper energy, cars, and consumer goods. This gives BoI Governor Amir Yaron room to cut rates without triggering inflation.
Here lies the trap. If the Bank of Israel cuts rates aggressively to save the exporters, capital flows out, weakening the shekel (good for tech). But doing so widens the ‘yield spread’ with the US Fed (currently at 3.75%), potentially triggering a chaotic capital flight rather than a controlled depreciation. Governor Yaron is walking a tightrope. He must devalue the shekel enough to protect the Israeli economy, but not so much that he triggers a bond market rout.
Israeli 2026 budget passes 62-55, but real battle moves to committees
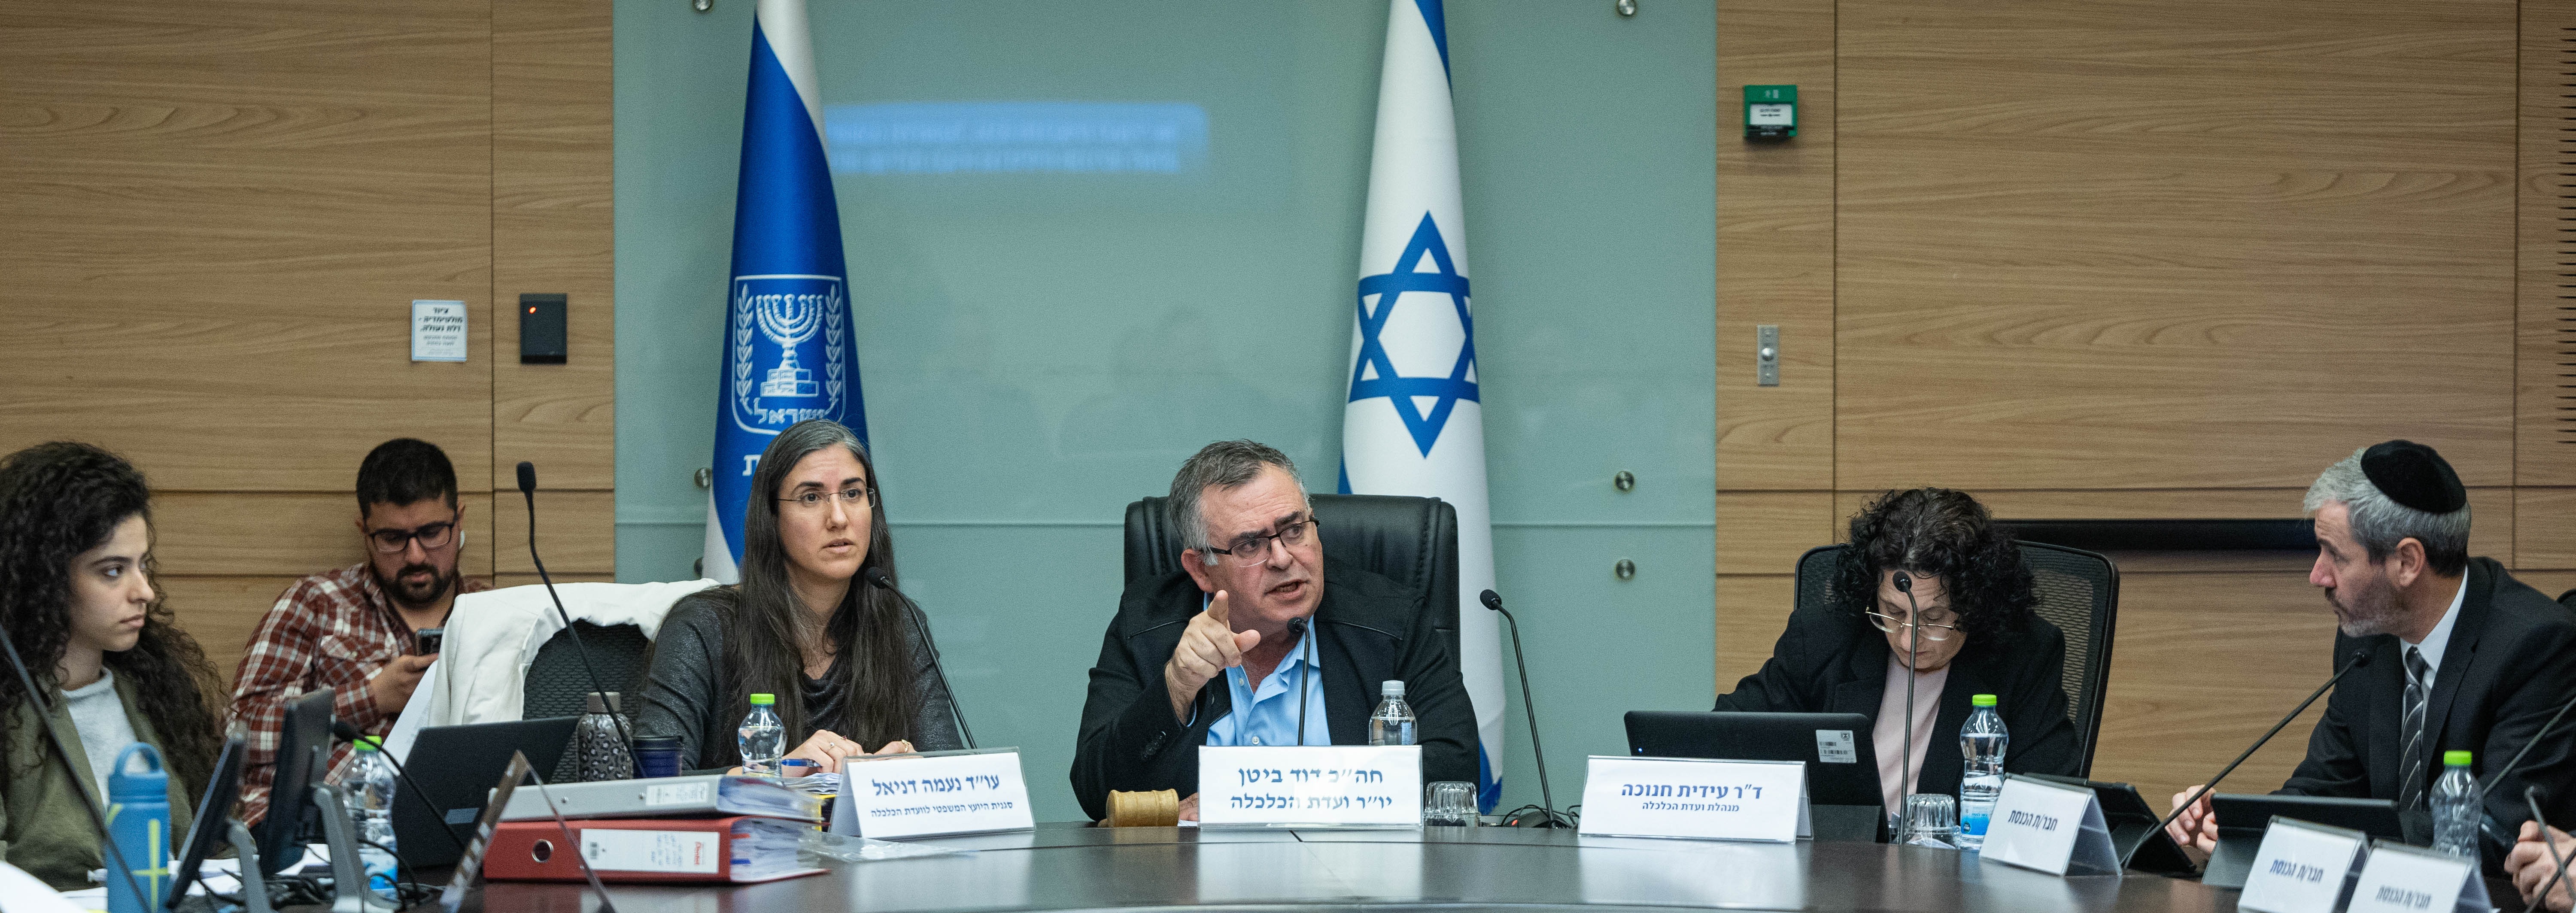
The Knesset approved the ₪662B state budget last week, but the Arrangements Law, containing structural reforms like the 15% bank excess profit tax, now faces committee warfare.
Finance Minister Smotrich is routing critical bills to friendly committees to bypass Economic Affairs Committee Chair MK David Bitan. Smotrich also publicly demanded Governor Yaron cut rates “by 1% or more, immediately.”
Our take - this is fiscal dominance, forcing the central bank to subordinate inflation control to government debt-service needs. The Bank of Israel’s icy response (“Not worthy of a comment,”) signals that Governor Yaron understands the game.
While the political echelon calls for easy money, the Accountant General’s data provides a sobering reality check. The Debt-to-GDP ratio climbed to 68.6% in 2025 (from 67.7%), driven by ₪207B in wartime debt. With a 3.9% deficit target for 2026, fiscal space is gone. The government can’t spook bond markets but needs spending for political survival.
Apple acquires Israeli audio-AI startup Q
While the headlines remain fixated on currency volatility and the friction of the budget debates, the underlying capital flows are telling a far more resilient story.
This week, Apple (NASDAQ:AAPL) announced the acquisition of Israeli startup Q, an audio-AI pioneer. Apple’s Senior VP Johny Srouji explicitly highlighted the team’s “exceptional” capabilities, marking a second home run for founder Aviad Maizels (who sold PrimeSense to Apple in 2013).
This corporate vote of confidence tracks with the sovereign data. According to the Accountant General, despite the geopolitical firestorm of the last year, Israel successfully raised over half a trillion shekels in debt. Crucially, this issuance was met with robust demand from global investors, not just local institutions.
Whether it is a tech giant securing talent in Herzliya or a global fund buying bonds in Jerusalem, smart money is effectively looking past the immediate deficit. They are taking a long position on Israel’s fundamental assets, technology and infrastructure. The prevailing thesis - once the geopolitical risk premium eventually evaporates, the economy’s true “terminal value” will be undeniable.
That’s our letter, folks. If you enjoyed this Weekly, forward it to a friend.
The English TV10 newsletter is edited by Sophia Tupolev. We love to hear from you.
TV10 Global | Israel for Investors
Now in English: Bringing you the top stories from the Israeli business community, by Israel’s only business and finance network.
Please share your thoughts with us via: [email protected] or the Newsroom WhatsApp: +972-55-994-5851.
📧 Subscribe to this newsletter! And follow the daily conversation on 𝕏 @tv10global.
Pings with new editions are also available via our WhatsApp Channel.
Disclaimer: This brief is for informational purposes only and does not constitute investment advice. All data is current as of publication date.