
Catching you up on the week’s top stories in the Israeli business community
For more details, read our daily editions from Monday to Wednesday
Moody’s upgraded Israel’s outlook to Stable, citing de-escalation of geopolitical risk and projecting 5% GDP growth for 2026. The agency also lifted The Phoenix’s financial strength rating to A3. Labor data showed resilience with December wages hitting ₪14,349 (+2.8% YoY) and high-tech salaries climbing to ₪31,332. The government approved a university for Kiryat Shmona and launched ₪600K grants to recruit specialist doctors to the Gaza Envelope.
The week’s biggest moves centered on energy infrastructure, Discount Bank signed an ₪800M financing deal for Israel’s largest solar-storage project in the Negev, while Delek Properties and Prime Energy announced a ₪930M plan to convert 65 gas stations into battery storage hubs. In real estate, Aviv Melisron and Acro won a ₪3B Jerusalem renewal tender, Dan Hotels acquired a Manhattan property for $125M, and Gav-Yam reported 97% occupancy with 10% NOI growth. Orion Security closed a $32M Series A for AI-powered data protection.
Editor’s note:
In 1909, a financial analyst named John Moody published the first ‘Manual of Railroad Securities,’ grading the debt of expanding American rail companies using a simple letter system. He invented a language that would eventually rule the global economy. For over a century, these ratings - AAA, Baa, C - have acted as the gatekeepers of global capital. They determine not just the interest rate a government pays on its bonds, but whether the world’s largest pension funds and endowments are even allowed to invest in a country at all.
For the past 18 months, Israel has been sitting in the penalty box. The Negative outlook attached to our credit rating was effectively a ‘Do Not Enter’ sign for conservative institutional capital in Tokyo, London, and New York. Investment committees are bound by strict mandates. They cannot allocate to sovereigns that are flagged for a potential downgrade. This created a disconnect, while local Israeli traders priced in resilience.
This week, the flow was unblocked. By upgrading Israel’s outlook from ‘Negative’ to ‘Stable’ and affirming the Baa1 rating, Moody’s didn’t just change a label, they reopened the financial borders. They are acknowledging that the geopolitical risk premium has structurally declined.
The implication is immediate. As you will read below, this sovereign green light has already cascaded down to the banks and insurers, lowering the cost of capital for the entire economy.
— Sophia Tupolev, TV10 Global Editor
TASE weekly snapshot
The Tel Aviv Stock Exchange closed the week mixed.
TA-35 Index (TASE:TA35): 🟢 +0.43%
TA-90 (TASE:TA90): 🔴 -3.02%
TA-125 (TASE:TA125): 🔴 -0.34%
Macro | Moody’s V-shaped bet on the Israeli economy
The ‘Negative’ tag is gone, and with it, the fear of a credit spiral. Moody’s cited the de-escalation of geopolitical risks - specifically the conclusion of direct conflict with Iran and stable ceasefires with Hamas and Hezbollah - as the catalyst for stabilizing Israel’s outlook. But the real story is in the growth forecast.
Moody’s is betting on a sharp V-shaped recovery, forecasting 5% GDP growth in 2026, leveling off to a healthy 3-3.5% annually thereafter.
While the outlook is stable, the war’s price tag is permanent. Government debt-to-GDP is stabilizing around 68%, but the agency notes debt levels will remain ~18 percentage points higher than pre-2023 forecasts in the medium term.
Accountant General Yali Rothenberg, who has spent the last two years managing debt auctions under fire, framed this as a correction of perception. He correctly noted that the markets had already priced in this stability via tightening spreads long before the analysts in London updated their spreadsheets.
Our take: This upgrade unlocks foreign institutional capital that was sidelined by mandate restrictions. Expect a compression in bond yields and a strengthening shekel. This currency strength gives the Bank of Israel a critical tool, it can now cut interest rates to stimulate that 5% growth without fearing it will trigger inflation via a weak currency.
Banking & Insurance | The liquidity fortress
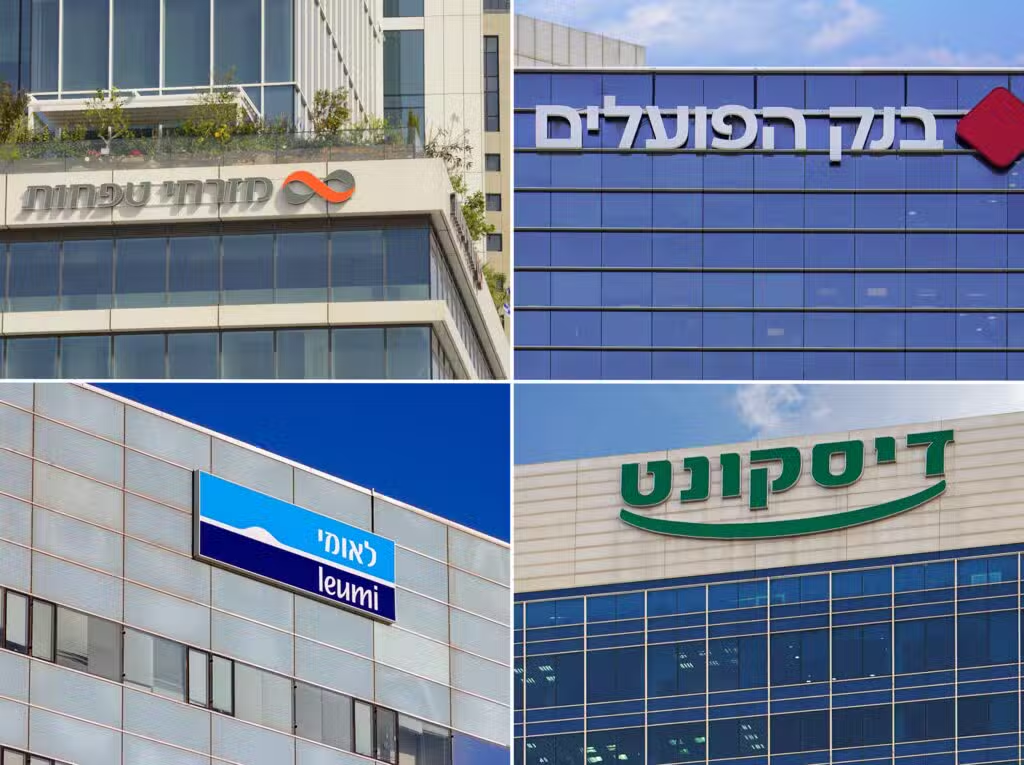
Sovereign ratings act as a ceiling for corporate ratings; a bank cannot be safer than the country it lends in. Therefore, the moment Israel’s outlook stabilized, the dam broke for the financial sector. Moody’s swept through the banking system, affirming ratings and upgrading the outlook to ‘Stable’ for the ‘Big Five’: Bank Leumi (TASE:LUMI), Bank Hapoalim (TASE:POLI), Mizrahi Tefahot (TASE:MZTF), Discount Bank (TASE:DSCT), and FIBI (TASE:FIBI).
Beyond the outlook, Moody’s raised Israel’s banking Macro Profile to ‘Strong-’ from ‘Moderate+.’ This is technical jargon for a fortress.
The resilience metrics are staggering. Despite a two-year war, Non-Performing Loans (NPLs) remain microscopic (0.4% - 1.0%). Even more impressive is the Liquidity Coverage Ratio (LCR), which averages a massive 128%. This means for every dollar of potential short-term outflow, the banks hold $1.28 in cash.
The only red flag remains the sector’s heavy exposure (13%-26%) to real estate and construction, sectors sensitive to interest rates.
Our take: The banks have effectively been stress-tested by a live war and passed with flying colors. With the Macro Profile upgrade, their cost of raising debt abroad will drop significantly. This widens their Net Interest Margin (NIM) - the spread between what they pay for money and what they charge you for it. We may see record profitability continue into 2026.
The rising tide lifts the insurers, but with higher leverage. The Phoenix Holdings (TASE:PHOE) saw its financial strength rating upgraded to A3 (Stable).
Moody’s highlighted the company’s ‘dominant market position’ and strong capital buffers. However, the rating is technically capped at A2 due to the company’s high correlation with the Israeli economy.
The agency warned that a drop in the Solvency Ratio below 130% or volatility in the Nostro (proprietary trading) portfolio could trigger a reversal.
Opinion | The Ratings Rorschach Test
The Moody’s upgrade is a fact. But what it signals depends entirely on where you sit. Is this the start of a roaring recovery, or simply a recognition that the worst-case scenario didn’t happen?
Ronen Menachem, Chief Markets Economist at Mizrahi Tefahot (TASE:MZTF), advises investors to keep the champagne on ice. His thesis is that the markets are smarter than the rating agencies. “The capital markets, stocks, the shekel, and CDS spreads, had already priced in this stability long before the report,” Menachem notes.
Therefore, don’t expect a massive additional rally. While the outlook improved, the structural damage is visible. Menachem points to the ‘Debt Gap’ a massive 18% of GDP (₪360 billion) difference between where Moody’s thought our debt would be pre-war versus where it is now. With 2026 being an election year and the budget still unapproved, “fiscal uncertainty remains high.”
For outgoing Accountant General Yali Rothenberg and the Ministry of Finance, the report is a victory lap. The upgrade validates the ‘Resilience Doctrine’ that the Israeli economy can absorb massive kinetic shocks without breaking. Rothenberg emphasizes that Israel’s ability to raise capital during the war (half a trillion shekels) proved the rating agencies wrong in real-time. For the Treasury, this isn’t just a stability upgrade; it’s a green light to lower the cost of servicing that massive debt pile.
Buried in the analysis is a warning that transcends economics. Menachem highlights the ‘ESG Penalty.’ Moody’s explicitly noted that Israel’s rating could be higher if not for ‘institutional and social risks,’ a polite euphemism for the lingering judicial reform tensions and governance issues. As long as the ‘Scorecard of Nations’ views Israel’s internal governance as shaky, there is a hard glass ceiling on how high our rating can climb, regardless of how many startups we exit.
That’s our letter, folks. If you enjoyed this Weekly, forward it to a friend.
The English TV10 newsletter is edited by Sophia Tupolev. We love to hear from you.
TV10 Global | Israel for Investors
Now in English: Bringing you the top stories from the Israeli business community, by Israel’s only business and finance network.
Please share your thoughts with us via: [email protected] or the Newsroom WhatsApp: +972-55-994-5851.
📧 Subscribe to this newsletter! And follow the daily conversation on 𝕏 @tv10global.
Pings with new editions are also available via our WhatsApp Channel.
Disclaimer: This brief is for informational purposes only and does not constitute investment advice. All data is current as of publication date.